Join a community of professionals and get:
on all CeFPro events.
unlock speaker decks and audience polls.
Full library access the moment you sign up.
- Chime plans to
acquire banking partner Stride Bank for $590 million in cash
- CEO Chris Britt says
becoming a bank will accelerate product launches and give Chime greater
control over its future
- AI is increasing
pressure to develop and deliver new financial products more rapidly
- Owning Stride could
reduce funding costs and eliminate bank partner fees
- Chime expects bank
status to strengthen trust among consumers wary of fintech banking models
- A national charter
could support geographic expansion and a broader range of lending products
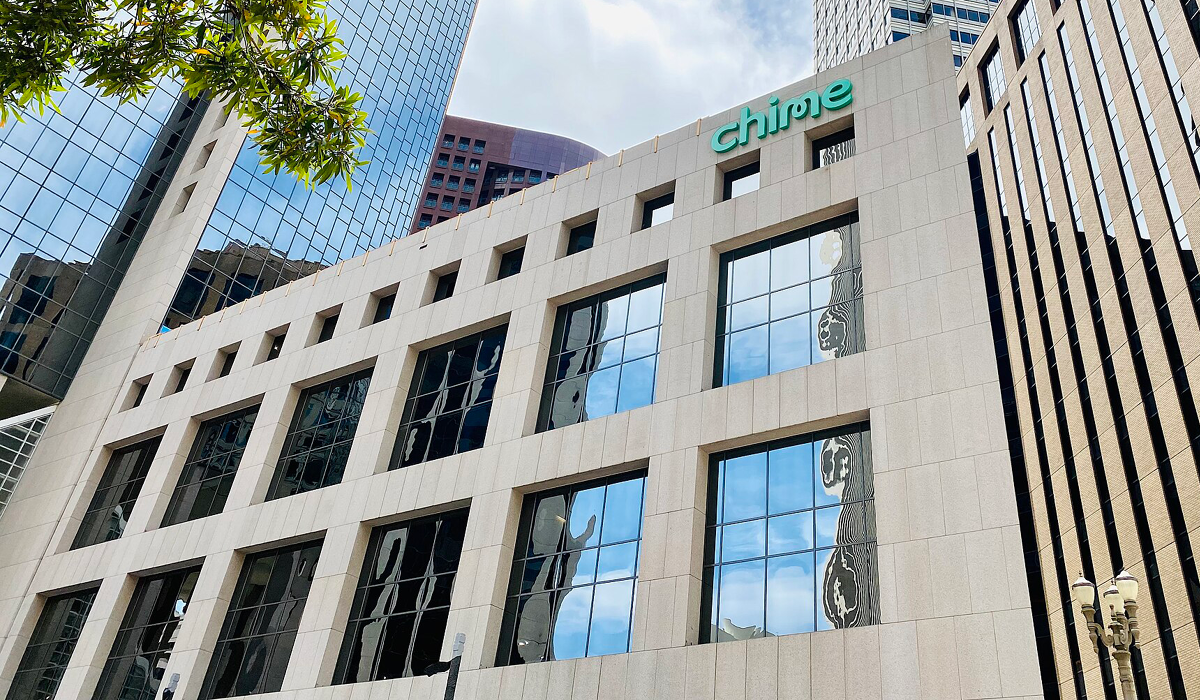
Chime’s proposed $590 million
acquisition of Stride Bank will allow the fintech to accelerate product
launches, cut costs and strengthen customer trust by bringing banking
infrastructure directly under its control, according to CEO Chris Britt.
San Francisco-based Chime announced
plans this week to acquire Enid, Oklahoma-based Stride, one of its existing
banking partners.
The transaction would combine Chime’s
technology platform with Stride’s banking infrastructure, while eliminating
partner fees and potentially reducing funding costs.
Speaking at a Goldman Sachs investor
conference, Britt described becoming a bank as an “inevitability” if Chime was
to achieve its ambition of becoming a leader in banking.
The timing has been influenced by
both a more receptive US regulatory environment and the increasing speed of
technological development.
Britt argued that artificial
intelligence is allowing financial companies to develop products and services
considerably faster, making control over the entire development and delivery
process increasingly important.
“With artificial intelligence, you
can create new products, new services, new experiences faster than you ever
could,” Britt said.
“When we look at all the innovation,
how quickly things are changing in the age of AI, we have to have full control
of the product output and delivery cycle.”
Chime’s existing partnership model
has required regulated products to undergo legal, compliance and other reviews
involving both Chime and its partner banks.
Although Britt said those
arrangements had not prevented Chime from introducing products, the additional
stages had sometimes slowed development.
“There’s no question that we haven’t
been able to move as fast as we would like,” he said, pointing to differences
in risk tolerance and compliance perspectives between Chime and its banking
partners.
Owning a charter should allow the
company to streamline those processes while giving it greater control over the
resilience of its underlying banking platform.
“We are at a size and a scale when we
need to have complete control of our destiny,” Britt said.
The move comes as fintech companies
increasingly pursue banking charters, either through applications or
acquisitions. SmartBiz, Enova and OppFi have pursued bank purchases, while
companies including Upstart, Affirm and PayPal have sought their own charters
amid greater regulatory openness to new banking models and consolidation.
For Chime, however, Britt believes
becoming a bank could deliver benefits extending beyond operational efficiency.
He argued that directly associating
the Chime brand and app with a regulated bank could reassure consumers who
remain uncomfortable holding money through fintech platforms reliant on
third-party institutions for Federal Deposit Insurance Corp. coverage.
“More directly connecting Chime brand
and Chime app to a bank is most certainly going to unlock greater levels of
trust for certain segments of the population,” Britt said, adding that some
customers simply “want it all from one provider.”
The acquisition could also
significantly expand Chime’s lending ambitions. Britt said owning a national
charter would create opportunities to enter geographic markets previously
unavailable to the company and support the development of additional credit products.
Chime is already testing an unsecured
revolving credit line among a group of loyal, higher-income customers and
expects to expand its lending offering over time.
Acquiring Stride, which has
approximately $5.4 billion in assets, would also enable Chime to hold consumer
deposits directly and use them to fund lending.
Under its existing arrangements,
customer deposits are held by partner banks, which can subsequently provide
funding to Chime for its credit activities. Removing that additional stage
should create greater flexibility and efficiency.
The deal therefore represents
considerably more than a change in Chime’s regulatory status.
If completed, it would transform the
fintech from a technology company operating alongside banking partners into an
institution controlling much more of its own financial infrastructure.
For Britt, that control appears
increasingly essential as AI accelerates the pace at which financial products
can be developed – and competition between traditional banks and their fintech
challengers intensifies.