
From Compliance to Resilience: Embedding Sustainability Risk into Financial Decision-Making
- Sustainability
risk integration remains constrained by data availability and challenges
linking sustainability factors to financial risk metrics.
- Firms should
adopt modular risk management frameworks that can evolve alongside
regulation and emerging evidence.
- Governance
structures are maturing, but accountability and risk appetite translation
remain key weaknesses.
- Physical
climate risk is expected to become a routine prudential management
consideration over the next three to five years.
- Resilient
institutions will use sustainability insights to actively influence
pricing, limits, capital allocation, and strategic decision-making.
As
sustainability risks become increasingly relevant to financial institutions,
firms are facing growing pressure to move beyond disclosure requirements and
embed sustainability considerations into existing risk management frameworks.
In this Q&A, Arjun Mahalingam, Head of Risk at United Nations Environment
Programme Finance Initiative (UNEP FI), shares insights on the practical
challenges of sustainability risk integration, governance, risk appetite,
adaptation, and what distinguishes truly resilient institutions.
1. What
are the biggest practical barriers to day-to-day integration?
In my view, the key barrier to day-to-day
integration is translating sustainability considerations into the language and
mechanics of mainstream risk management. The UNEP FI Risk Centre’s Landscape of Sustainability Risk
Integration report identifies data constraints as the dominant
implementation challenge, alongside difficulties converting third-party
sustainability outputs into financial metrics and embedding them within
existing risk models.
Credit risk remains the most advanced area
of integration, but embedding sustainability into capital models is still
limited, while quantification of market and operational risks continues to lag.
The challenge is even greater for nature, pollution, and social risks, where
data, methodologies, and regulatory expectations remain less developed.
At the UNEP FI Risk Centre, our focus has
been on helping banks and insurers connect sustainability drivers to existing
risk parameters, underwriting criteria, risk registers, limits, and management
actions rather than creating separate, standalone frameworks.
2. How should firms build robust capabilities without creating processes that quickly become outdated?
These foundations provide a stable
structure, while methodologies, scenarios, data sources, and thresholds remain
flexible and adaptable. Importantly, uncertainty around data should not become
a reason for inaction. Instead, it reinforces the need for a structured and
systematic approach that can accommodate new evidence as it emerges.
3. Where
are institutions falling short on governance and risk appetite?
The primary challenge is not a lack of
governance structures, but the limited translation of board-level oversight
into accountable business decisions at portfolio, business-line, and
counterparty level.
According to UNEP FI Risk Centre research,
governance is one of the most mature aspects of sustainability risk
integration. However, reporting often lacks clear links to credit limits,
provisioning, capital assessments, internal models, and risk appetite
frameworks. Progress is particularly uneven outside climate risk.
The greatest opportunity for improvement
lies in translating high-level sustainability commitments into sector and
counterparty-specific thresholds, key risk indicators, escalation triggers, and
clearly assigned ownership. Boards should have visibility not only into
exposures but also whether risks sit within appetite limits, who is
accountable, and what action will be taken when thresholds are exceeded.
4. How will physical climate risk and adaptation affect prudential management over the next three to five years?
Over the coming years, physical climate risk
is likely to move from exploratory stress testing exercises into routine
prudential assessment. Financial institutions will increasingly need to
consider physical climate impacts alongside creditworthiness, collateral
valuation, operational resilience, and portfolio management.
UNEP FI research highlights links between
physical climate risk materiality assessments and broader banking activities,
including strategy, client engagement, capital allocation, and lending
decisions. This points toward greater scrutiny of asset locations, collateral
vulnerability, supply chain exposure, business continuity, and borrowers’
adaptation capabilities.
Adaptation should not be viewed simply as a
financing category, but as a potential risk mitigant whose effectiveness and
durability can be assessed. The focus will increasingly shift from measuring
vulnerability to understanding whether adaptation actions meaningfully reduce
expected risk and strengthen resilience.
5. What
will distinguish genuinely resilient institutions?
Compliance-focused institutions will
complete the required assessments and disclosures. Truly resilient
institutions, however, will use that information to influence decisions.
The key differentiator will be an
organisation’s ability to translate forward-looking sustainability information
into meaningful business and risk management actions. Resilient firms will
combine granular counterparty and asset-level data, transparent methodologies,
portfolio-specific scenarios, actionable key risk indicators, and skilled
professionals capable of converting sustainability drivers into conventional
risk metrics.
Most importantly, these institutions will
connect sustainability assessments directly to pricing decisions, client
engagement strategies, portfolio steering, risk limits, business continuity
planning, and capital allocation. Developing these capabilities is challenging,
which is why the UNEP FI Risk Centre’s sustainability risk integration
frameworks provide a practical blueprint for institutions at different stages
of their journey.
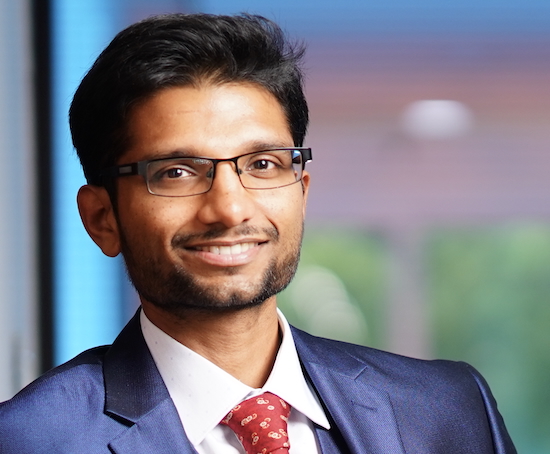
Head of Risk Centre, United Nations Environment Programme Finance Initiative
Arjun currently heads the UNEP FI Risk Centre, where he oversees strategic projects that delivers technical resources and tools to support sustainability risk integration within financial institutions. He is on the advisory board of Nature-3B and Global Association of Risk Professionals (GARP). Before joining UNEP FI, he led the Bank of England’s global engagement on international climate issues where he advised the Governors and seniors on their international engagements in the G7, G20, FSB and NGFS on a range of sustainability-related issues. He has actively led and contributed to analytical and policy work in international working groups and domestic policy work related to climate risk assessments, transition plans and prudential regulation. He also led projects on climate risk management and energy transition-related issues at the Cambridge Judge Business School (CJBS) at the University of Cambridge, UK. He holds academic degrees from the London School of Economics and Political Science (LSE), TU Delft and the University of Delhi; and professional certifications from GARP and the University of Oxford. He has conducted academic research at National University of Singapore (NUS) and Massachusetts Institute of Technology (MIT).
LinkedIn profile




